Jump to a section
At a glance
Key takeaways
- The historical licence-month deadlines for companies existing before 1 March 2024 have passed, but the registration obligation remains relevant.
- A juridical person established in the UAE on or after 1 March 2024 generally applies within three months from incorporation, establishment or recognition.
- A natural person generally registers when UAE Business or Business Activity turnover exceeds AED 1 million, within the applicable Decision No. 3 of 2024 timeline.
Why the registration timeline page needs current context
The licence-month deadlines widely published in 2024 applied to Resident Juridical Persons incorporated or established before 1 March 2024. Those dates have passed, but an unregistered taxable person should not assume the obligation disappeared. The correct action is to establish the applicable category, apply promptly and assess the current penalty-waiver rules.
Resident Juridical Persons established before 1 March 2024
FTA Decision No. 3 of 2024 assigned deadlines between 31 May and 31 December 2024 according to the month of the earliest licence issuance, regardless of the licence year. A person with no licence at the Decision’s effective date had a three-month period. These are historical deadlines and should be presented as such.
Resident Juridical Persons established on or after 1 March 2024
A juridical person incorporated, established or otherwise recognised under UAE legislation, including a Free Zone Person, generally applies within three months from its incorporation, establishment or recognition. A foreign juridical person effectively managed and controlled in the UAE generally applies within three months from the end of its financial year.
Non-Resident Juridical Persons
A Non-Resident Juridical Person with a UAE Permanent Establishment or nexus follows the category-specific periods in Decision No. 3 of 2024. The triggering date and whether a Permanent Establishment or nexus exists are legal and factual questions; they should be documented before calculating the deadline.
Natural Persons
A natural person generally enters UAE Corporate tax where Turnover from a UAE Business or Business Activity exceeds AED 1 million in a Gregorian calendar year. A Resident Natural Person generally registers by 31 March of the following year. A Non-Resident Natural Person generally registers within three months from meeting the conditions for being subject to tax.
Late registration penalty and waiver initiative
The FTA states that late Corporate tax registration carries an AED 10,000 administrative penalty. Its current waiver initiative can remove or reverse that penalty when the taxable person files the first Corporate tax Return—or the relevant annual declaration for an exempt person—within seven months from the end of the first tax period, subject to the initiative’s conditions.
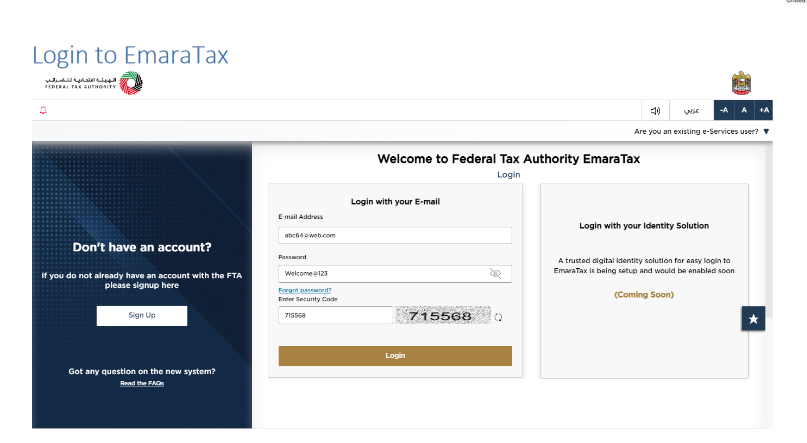
How to register through EmaraTax
- Create or access the EmaraTax account and the correct Taxable Person profile.
- Open the Corporate tax registration action for that profile.
- Complete legal, licence, ownership, contact and financial-year details.
- Upload consistent supporting documents and submit the application.
- Retain the submission acknowledgement and monitor FTA requests.
Common registration risks
Using the wrong earliest licence month, omitting a Free Zone entity, confusing VAT registration with Corporate tax registration, creating duplicate profiles and choosing an incorrect first tax period can affect later returns. Registration data should agree with licences, constitutional records and accounting year-end information.
How SAIF Chartered Accountants can help
We can identify the applicable registration category and deadline, prepare the EmaraTax application, resolve data inconsistencies and coordinate the first Corporate tax Return and any available penalty-waiver conditions.
Authority and verification
Official sources
- UAE Federal Tax AuthorityFTA Decision No. 3 of 2024 — Corporate Tax registration timelineChecked 21 August 2026
- UAE Federal Tax AuthorityCorporate Tax registration service and current guidanceChecked 21 August 2026
- UAE Federal Tax AuthorityFTA registration-timeline public clarificationChecked 21 August 2026
Clear answers
Frequently asked questions
What if my 2024 Corporate tax registration deadline has passed?
Determine the applicable category, submit the registration promptly and assess the current FTA late-registration penalty-waiver conditions.
When does a new UAE company register for Corporate tax?
A UAE juridical person established on or after 1 March 2024 generally applies within three months from incorporation, establishment or recognition.
When must a natural person register?
A Resident Natural Person whose UAE Business turnover exceeds AED 1 million in a calendar year generally registers by 31 March of the following year.
What is the late Corporate tax registration penalty?
The FTA currently states an AED 10,000 administrative penalty, subject to the conditions of its late-registration penalty-waiver initiative.