Valuation · Modelling · Corporate advisory

Financial Consultancy Services in Dubai & UAE

Understand the value. Test the funding. Make an informed decision.

SAIF Chartered Accountants helps business owners, shareholders and management teams examine financial questions around investment, funding and change. We scope business valuations, financial models, funding preparation and transaction-related analysis around the decision you need to make.

For business decisions—not personal investment products or guaranteed finance.

Business owner and financial adviser discussing a report in a naturally lit office
Begin with the purpose.A shareholder discussion, a funding application and financial reporting may require different work.

A different question needs a different brief

Which financial decision are you facing?

Financial consultancy is most useful when the assignment has a clear purpose. Identify who will use the work, the relevant entity or ownership interest, the decision date and the evidence available.

Agree the assignment, not a generic package

Financial advisory services for UAE businesses

The following workstreams can be scoped individually or combined. Specialist work, formal reporting requirements and any required permissions must be assessed before appointment.

Business & share valuation

For an ownership discussion, investor entry, partner exit or internal decision, establish the interest being valued, the purpose and valuation date. Assess the available financial evidence and suitable methods.

A scoped valuation report should explain its basis, assumptions, limitations and intended users—not just present a headline number.

Financial modelling & projections

Build or review a model linking operating assumptions, profit and loss, balance sheet and cash flow. Examine investment spending, working capital, financing and downside scenarios.

Agree the forecast horizon, level of detail, model checks, editable-file delivery and update responsibility. A model review is not automatically an audit or assurance engagement.

Funding & refinancing preparation

Define why funding is needed, how much is required and when. Organise historical accounts, projections, existing facilities and supporting schedules for management’s lender or investor discussions.

Compare affordability, repayment timing and key sensitivities. Financing introductions, arranging credit or securities activity are not implied by this preparation service.

Financial restructuring analysis

Examine the financial effects of proposed changes to debt terms, business activities, ownership or group structure. Test cash requirements, implementation costs and the dependencies behind an improvement plan.

Financial analysis does not replace legal advice, formal insolvency procedures, creditor agreement or authority consent. Flag urgent solvency concerns at the outset.

Transaction decision support

Help management examine the financial implications of a proposed purchase, sale, merger or shareholder change. Connect the forecast, valuation assumptions and transaction funding.

Financial due diligence, legal documentation, tax structuring and specialist asset assessments need their own agreed scope and responsible advisers.

Financial reporting & accounting advisory

Assess the accounting information and reporting issues connected with a transaction or change in the business. Identify gaps in schedules, assumptions, controls and the supporting evidence.

Confirm the applicable reporting framework and specific technical question. Statutory accounts, valuation for financial reporting and audit work must be clearly distinguished.

Business valuation & shareholder decisions

“How much is my company worth?” starts with “for what purpose?”

A whole business, a controlling stake and a minority interest are not interchangeable. Agree the valuation date, basis of value, interest and intended use before comparing methods or discussing a price. A negotiated transaction price can differ from the valuation conclusion.

Income-based analysis

Discounted cash flow (DCF) analysis examines expected future cash flows and the risks reflected in the discount rate. Forecast credibility, capital needs and the terminal assumptions matter.

Market-based analysis

Use relevant transaction or trading evidence where available. Differences in size, growth, profitability, risk and the rights being valued need consideration; not every published multiple is comparable.

Asset-based analysis

Assess the underlying assets and liabilities where appropriate to the business and purpose. Book value is not automatically current value, and individual assets may require specialist assessment.

Questions that change the analysis

  • Are earnings sustainable, or influenced by one-off items?
  • How dependent is the business on its owner or a major customer?
  • What debt, cash, commitments and related-party balances exist?
  • Which ownership rights and restrictions apply?
  • What evidence supports forecasts and comparable data?

Value is not a guaranteed selling price

Enterprise value and shareholder equity value answer different questions. Debt, cash and other adjustments must be treated consistently with the method and deal terms. Share rights, restrictions and the transaction context also matter.

The IVSC valuation glossary explains concepts such as income approach, intended use and investment value. The engagement must identify the applicable basis and standards; this reference is not an assertion that every assignment is an IVS valuation.

Funding preparation & financial modelling

A funding request should explain the cash requirement—not just name an amount.

A model should show how the business operates, when investment is paid for and how cash becomes available. Connect revenue, costs, working capital, capital expenditure and financing rather than preparing disconnected forecasts.

Ask what changes under slower sales, delayed collections, cost increases or revised borrowing terms. Base-case profitability alone does not establish affordability.

  1. 01 · Uses

    What will the money fund?

    Separate setup, expansion, working capital, refinancing and transaction costs.

  2. 02 · Sources

    Where will the money come from?

    Distinguish committed resources from proposed equity, borrowing or asset proceeds.

  3. 03 · Timing

    When is the peak shortfall?

    Model drawdowns, receipts, payments and minimum cash assumptions over time.

  4. 04 · Resilience

    What if the plan changes?

    Test repayment capacity, covenant definitions and the downside case.

Preparation is not financing approval

We can help organise the financial case and supporting schedules within the agreed scope. A bank or investor determines its own information requirements, provider acceptance, terms and decision. This service does not promise a loan, investor introduction or a particular valuation.

Look beyond the headline transaction

Financial analysis for acquisitions, refinancing and restructuring

Before changing ownership

Define what is being bought or sold, what information is available and how the price will be determined. Use financial due diligence to investigate historical performance and exposures; a valuation or projection does not perform that work automatically.

Model funding, transaction costs and post-deal cash needs. Legal advisers should address agreements, warranties, rights and completion mechanics.

Before changing debt or operations

Assess cash availability, facility terms, maturity dates and the effect of proposed changes. Separate operational improvements from assumptions that depend on creditors, owners or third parties.

Where the company is under financial pressure, identify immediate obligations and obtain appropriate legal and insolvency advice promptly. Financial analysis cannot itself change creditor rights or approve a formal restructuring.

Before using figures in financial statements

Specify the reporting purpose, framework and evidence required. A transaction negotiation model and a financial-reporting valuation may have different assumptions and requirements.

The IFRS Foundation explains that IFRS 13 provides a fair-value measurement framework when required or permitted by another applicable Standard, subject to its scope. It is not a universal basis for every company valuation.

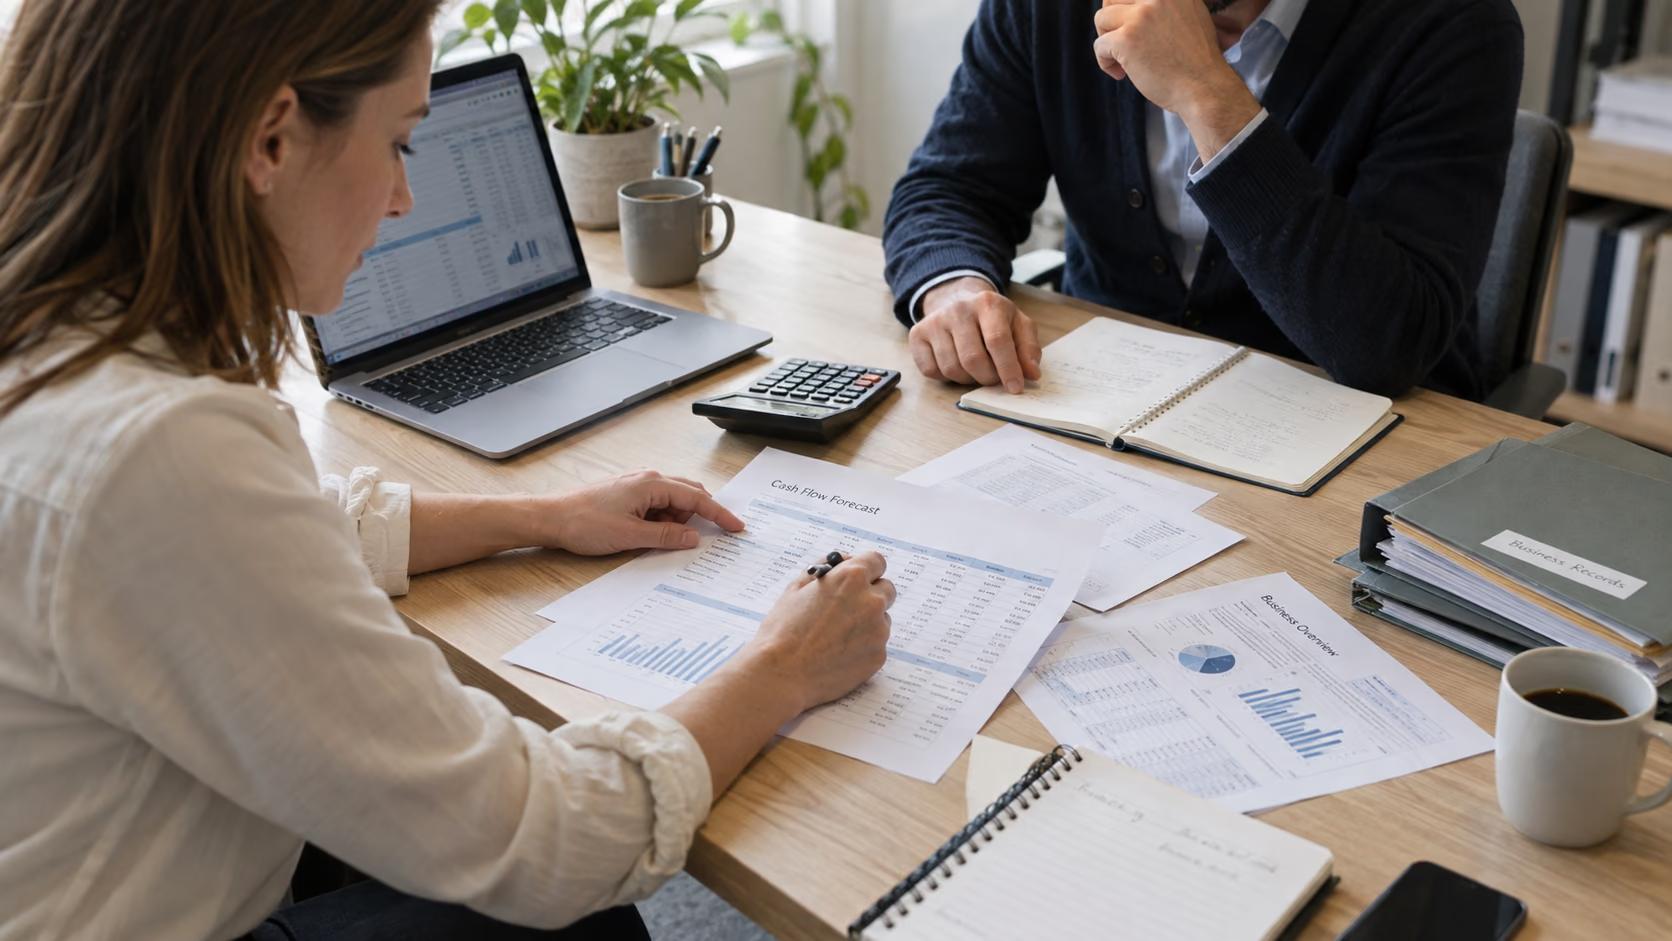
Colleagues reviewing a cash-flow forecast and business records beside a laptop and calculator
A well-organised evidence pack makes assumptions and unresolved questions easier to review.

Prepare a useful starting point

Documents needed for financial consultancy

Start with the records already available. Tell us which figures are final, draft, estimated or unaudited. Do not substitute a large folder of files for reconciled schedules and clear explanations.

  • Trade licence, group structure, ownership and share rights.
  • Recent financial statements and current management accounts.
  • Trial balance, bank reconciliations and aged balances.
  • Forecasts, budgets and the assumptions behind them.
  • Borrowing agreements, repayment schedules and security details.
  • Major contracts, asset schedules and related-party balances.
  • Transaction terms or the recipient’s report checklist.

Match information to the purpose

A shareholder valuation may require different evidence from a refinancing analysis. Set the request list after confirming the scope. Material gaps can require further accounting work or limit what can be concluded.

Control access and versions

Use an agreed secure route for financial records. Identify document owners, restrict access, and maintain an assumption log. Clarify who approves inputs and how later changes will be handled.

Mainland · Free zones · Groups

Keep entity, tax and transaction questions connected

For UAE SMEs, family businesses and groups, the financial question may cross more than one company, currency or jurisdiction. Confirm the entities and interests covered before combining figures.

Legal entities & intended users

Identify whose financial position is being analysed and who may rely on the report. A group forecast does not replace the evidence needed for an individual company, branch or shareholder interest.

Tax assumptions

Coordinate Corporate tax, VAT and related-party pricing where relevant. Detailed tax treatment requires its own fact-specific analysis, not a generic assumption that applies to every entity.

Sector-specific evidence

A trading business may depend on stock and customer credit; a project business on completion and collection; an asset-intensive business on capital expenditure and asset condition. Identify specialist input rather than treating every model alike.

A defined project with a clear handover

How the assignment works

  1. 01

    Agree the brief

    Confirm purpose, date, entities, users, deliverables, methods to consider and exclusions. Check any recipient or independence requirements.

  2. 02

    Review the evidence

    Assess the records, reconcile significant schedules and identify missing information or assumptions needing support.

  3. 03

    Analyse and challenge

    Prepare the agreed calculations and scenarios. Discuss differences, limitations and the impact of alternative assumptions.

  4. 04

    Report and hand over

    Explain conclusions and dependencies. Agree the files delivered, permitted use, revisions and any follow-up work.

What should you receive?

Agree the report or memorandum, model and schedules, assumption register, sensitivity analysis and management discussion. Confirm whether editable files, presentations, recipient queries and later updates are included.

Fees and timing

No fixed plans apply to every company. Scope, data quality, complexity, methods, number of entities, specialist work and intended report use determine the quotation and milestones. Identify a bank or transaction deadline before work begins.

Management retains its decisions and responsibilities. Personal investment advice, lending, regulated arranging, legal representation, specialist asset valuation and audit assurance are not implied by a general financial consultancy engagement. Suitability, permissions, conflicts and independence must be checked for the actual assignment.

Request a scoped financial review →

Questions before commissioning the work

Financial consultancy FAQs

What does a financial consultant do for a business in Dubai?

A financial consultant analyses a defined business finance question and explains the evidence, options and risks. Work can include business valuation, financial modelling, funding preparation, transaction analysis or reporting support. SAIF agrees the purpose, intended users, deliverables and limitations before starting. This page concerns business advisory, not personal wealth management.

How is financial consultancy different from outsourced CFO support?

Financial consultancy commonly addresses a defined assignment, such as valuing an interest, reviewing a model or preparing a funding case. Outsourced CFO support usually provides an ongoing cycle of management reporting, cash planning and advice. They can work together, but the scope and responsibilities should remain distinct.

Can you help me understand what my company is worth?

A business valuation can be scoped after establishing the purpose, date, ownership interest and information available. Methods may consider expected cash flows, relevant market evidence and the underlying assets and liabilities. A valuation conclusion is not a guaranteed selling price, and a buyer may negotiate on a different basis.

Is a company valuation simply a multiple of profit or revenue?

No single multiple is suitable for every company. Results can be affected by sustainable earnings, growth assumptions, customer concentration, owner dependence, debt, capital needs and the rights attached to the interest. Comparable evidence must be relevant and any adjustments explained. A headline industry multiple is not a substitute for an assessment.

What is the difference between enterprise value and equity value?

Enterprise value generally refers to the value of the business operations independently of how they are financed. Equity value concerns the interest attributable to shareholders. Moving between them requires a consistent treatment of debt, cash and other relevant items. The treatment depends on the valuation basis and transaction terms; a simple subtraction should not replace that analysis.

Can SAIF prepare financial projections for a bank or investor?

We can scope projections and supporting financial schedules using the agreed business assumptions and available evidence. Obtain the recipient’s requirements before commissioning the work. Forecasts should state their period, assumptions, risks and permitted use. The bank or investor decides whether the information and provider are acceptable and whether to provide funding.

Do you provide loans, guarantee finance or find investors?

This page offers financial analysis and preparation, not lending, underwriting or a guarantee of investment. Do not assume that introductions, arranging finance, securities advice or transaction execution are included. Any such request needs a separate assessment of the service, relevant permissions and appropriately authorised parties.

What documents are needed for financial consultancy?

Start with the business brief, ownership and entity details, recent financial statements, management accounts, trial balance, forecasts, debt schedules and relevant contracts. A valuation or transaction may also require information on customer concentration, assets, related parties and shareholder rights. The final request list depends on the assignment.

Can you work with incomplete or unaudited accounts?

We first assess whether the information is sufficient for the intended purpose. Reconciliations, accounting corrections or additional evidence may be needed before analysis can be relied on. Unaudited information must be identified as such. Material gaps may limit the scope or prevent a supportable conclusion; we do not fill them with unexplained assumptions.

Can the report be used for a share transfer, court or regulatory submission?

Confirm the intended use, required format and accepted provider with the recipient before appointment. A report prepared for internal planning may not be suitable for a court, regulator, bank or formal share-transfer procedure. Do not assume universal acceptance or that every statutory valuation requirement is covered by a general consultancy engagement.

Does a valuation have to follow IFRS 13?

The applicable basis depends on why the valuation is needed. IFRS 13 concerns fair value measurement and disclosures when another applicable IFRS Standard requires or permits them, subject to its scope exceptions. It is not automatically the basis for every business-sale negotiation or internal valuation. Agree the applicable framework and purpose before the work starts.

Do you support UAE mainland, free-zone and group companies?

The assignment can be scoped for mainland or free-zone businesses, branches or groups. Identify the legal entities, ownership interests, currencies and intended report recipients. Consider the relevant tax, legal and regulatory questions separately; a group model or free-zone address alone does not settle them.

How much does financial consultancy cost, and how long does it take?

Fees and milestones depend on the company profile, assignment complexity, entities, information quality, methods, intended users and specialist input. SAIF does not apply one fixed plan to all companies. Agree the deliverables, revision allowance, meetings and any additional work after the initial information assessment.

Can your audit firm also prepare our valuation or financial model?

The proposed assignment needs an independence and conflict assessment before acceptance, especially if its output could be material to financial statements we audit. Some work may need an independent provider. A consultancy report is not an audit opinion, and management remains responsible for its decisions and information.

How should I choose a financial consultancy firm in the UAE?

Explain the exact decision and ask the firm to confirm the suitable scope, relevant experience, responsible adviser, methods, information needed and intended report use. Compare exclusions and follow-up support as well as fees. Be cautious about guaranteed finance, guaranteed valuations or claims that any report will be accepted by every recipient.

Start with your decision

Tell us what you need to understand.

Share the business context, intended report use and decision date. We will help define the financial analysis and information needed for the assignment.

Contact SAIF Chartered Accountants →