Jump to a section
At a glance
Key takeaways
- Match the benchmarking method and evidence to the transaction; a loan, service fee and salary are not the same analysis.
- Separate documentation and disclosure thresholds from the underlying obligation to support arm’s-length pricing.
- Record screening decisions and assumptions so the results can be reproduced and reviewed.
- A result within a range is not a guarantee of acceptance; the quality of the underlying analysis matters.
A transfer pricing benchmarking study helps a UAE business assess whether its related-party prices or margins reflect arm’s-length conditions. This guide explains how to choose an approach, document comparable evidence and interpret the results, with practical examples for businesses in Dubai and across the UAE.
In brief: understand the transaction first, choose an appropriate method, evaluate comparable evidence, and explain the conclusion. A profit-margin study, a loan-interest analysis and a director-remuneration assessment are different exercises; one template cannot answer every question.
Table of Contents
- What is a transfer pricing benchmarking study?
- When is a benchmarking study required in the UAE?
- The arm’s length range and the interquartile range
- The five OECD transfer pricing methods
- Choosing the right profit level indicator (PLI)
- The benchmarking study process — step by step
- Which databases are used for UAE benchmarking?
- The FTA’s geographic search hierarchy
- Low value-adding services: the 5% simplified approach
- Connected persons and KMP remuneration
- Five benchmarking mistakes to avoid
- A worked example: reading the range
- What a benchmarking report should contain
- How SAIF Chartered Accountants can help
- Official sources
- Frequently asked questions
What is a transfer pricing benchmarking study?
Transfer pricing concerns transactions between related parties, including a company and its parent, subsidiary or sister company. It is relevant to domestic as well as cross-border arrangements. Benchmarking compares the transaction’s price, rate or margin with independent evidence, taking account of what each party actually does and the risks it bears.
UAE transfer pricing documentation sits within Federal Decree-Law No. 47 of 2022, as amended, and Ministerial Decision No. 97 of 2023. A Local File explains the entity’s relevant controlled transactions and supporting economic analysis; a Master File describes the wider group. A benchmarking report can support that documentation, but is not the same document as either file.
When is a benchmarking study required in the UAE?
Separate the obligation to maintain documentation from the choice of evidence used to support pricing. Reliable internal comparables can make an external database search unnecessary. The following thresholds concern documentation or reporting, not a universal requirement to purchase a benchmarking report:
| Requirement | Threshold or scope | Practical distinction |
|---|---|---|
| Local File / Master File | Taxable Person revenue of AED 200 million or more, or membership of an MNE group with consolidated revenue of AED 3.15 billion or more, in the relevant Tax Period. | Apply Ministerial Decision No. 97 of 2023, including Local File scope exclusions. UAE-only groups have a Master File exception under the FTA guide. |
| Related Party transactions schedule | Aggregate transactions exceed AED 40 million; report categories exceeding AED 4 million. | Apply the Tax Returns Guide’s calculation rules; related-party dividends are excluded from these thresholds. |
| Connected Persons schedule | Payments or benefits exceed AED 500,000 per Connected Person together with its Related Parties. | A disclosure threshold, not a tax-free salary allowance or an automatic deduction. |
| Country-by-Country Reporting (CbCR) | UAE-headquartered MNE group revenue of at least AED 3.15 billion in the preceding financial year. | Separate notification/reporting requirements for the UAE ultimate parent; not every UAE subsidiary above a group threshold files a CbC report. |
Documentation source: Ministerial Decision No. 97 of 2023, Article 2
Disclosure source: FTA Tax Returns Guide, sections 9.3 and 16
A business below a reporting threshold should still assess the underlying pricing rules and retain appropriate support, subject to applicable reliefs and exceptions. Free Zone status does not itself remove transfer pricing obligations. For financing arrangements, check the current return instructions rather than assuming that the closing loan balance and interest expense are treated identically.
The arm’s length range and the interquartile range
Independent comparables are never identical to your business, so a benchmarking study almost never produces a single “correct” price. Instead it produces a range of results. To reduce the effect of outliers, that range is usually narrowed to the interquartile range (IQR) — the results between the 25th and 75th percentiles.
- Inside the range — a result within a reliable arm’s-length range can support the pricing conclusion. This does not prevent the FTA from questioning the method, comparables or reliability of the range itself.
- Outside the range — if it falls below (or above) the range, the FTA can adjust. Importantly, the FTA may adjust the result to the point within the arm’s-length range that best reflects the facts and circumstances. The median can be relevant in some analyses, but it is not an automatic UAE rule.
The five OECD transfer pricing methods
Benchmarking always sits under a chosen method. The FTA accepts all five OECD methods:
- Comparable Uncontrolled Price (CUP) — compares the actual price directly; the most reliable method when good comparables exist (e.g. commodities, quoted rates).
- Resale Price Method (RPM) — works back from the resale price using a gross margin.
- Cost Plus Method (CPM) — adds an arm’s length mark-up to costs.
- Transactional Net Margin Method (TNMM) — compares a net profit indicator with independent comparable results.
- Transactional Profit Split Method — considers how combined profits should be allocated, for example where parties make unique and valuable contributions or have highly integrated activities. It is not limited to cases where both parties legally own intellectual property.
Choosing the right profit level indicator (PLI)
For TNMM, explain why the selected profit level indicator fits the transaction. Gross mark-ups under Cost Plus and net margins under TNMM are not interchangeable. The examples below illustrate possible approaches, not automatic rules based on a job title or industry label:
| Transaction / activity | Possible approach | Measure to explain |
|---|---|---|
| Routine distribution | TNMM where appropriate | Operating profit relative to sales |
| Routine support services | TNMM or Cost Plus where appropriate | Net return on relevant costs or a comparable gross mark-up; distinguish the two |
| Contract manufacturing | Method selected for actual functions and risks | Relevant cost, sales or asset-based return, with consistent accounting |
| Intercompany lending | Comparable interest-rate analysis | Interest rate for comparable financing terms, not a company operating margin |
| Director / executive services | Comparable remuneration evidence | Total reward for a comparable role and responsibilities |
Methodology reference: OECD Transfer pricing Guidelines 2022
The benchmarking study process — step by step
For an external comparable-company study, the following nine-step workflow is a practical starting point. Adapt it for internal comparables, loans, royalties and remuneration rather than forcing every transaction into a TNMM database search.
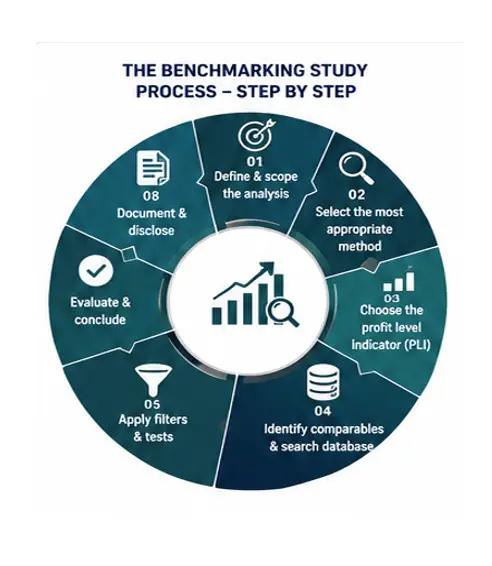
- Functional analysis (FAR). Characterise the tested party by the functions it performs, the assets it uses, and the risks it assumes — usually the least complex party is tested. Where intangibles are involved, apply the OECD DEMPE analysis.
- Identify the transaction and select the method. Classify each transaction (goods, services, financing, IP) and choose the most appropriate OECD method.
- Select the measure. For a TNMM study, justify the PLI and its denominator; a price-based method instead compares an appropriate price or rate.
- Define the search criteria. Industry codes, geography, independence, size, and data availability.
- Assess available evidence. Consider reliable internal comparables before an external database search. Where an external search is needed, retain the search strategy, date and results.
- Qualitative screening. Investigate loss-making comparables; exclude them only with a documented comparability reason, not merely because they made a loss.
- Calculate comparable results consistently. Explain the financial periods, accounting treatment and any use of multi-year data rather than applying a three-year average mechanically.
- Evaluate the range. Explain whether the full range or an interquartile range is appropriate, then compare the tested result on a consistent basis.
- Document the study. Compile the database, search date, screens, rationale, and conclusion into a benchmarking report retained for at least seven years.
Comparability and screening guidance: FTA Transfer pricing Guide, sections 5.3.2–5.3.5
Which databases are used for UAE benchmarking?
UAE benchmarking is typically performed using recognised commercial databases — Bureau van Dijk Orbis and Amadeus, and TP Catalyst by Moody’s — with specialised sources for royalty rates and financial transactions. What matters to the FTA is not just which database you used, but that the search date, screening criteria, and the accept/reject rationale for every comparable are documented and reproducible.
The FTA’s geographic search hierarchy
The FTA expects comparables to be sought in order of relevance, not convenience:
- UAE-incorporated independent companies in the same sector — the preferred first search.
- GCC and wider Middle East comparables — where domestic data is insufficient for a reliable set.
- Pan-European or global comparables — only where regional data is inadequate, with comparability adjustments documented.
Defaulting straight to a global comparable set when reliable UAE or regional data exists is a common methodology weakness that invites adjustment on audit.
Low value-adding services: the 5% simplified approach
Not every intercompany charge needs a full benchmarking search. Under the OECD simplified approach for low value-adding intra-group services (LVAIGS) — routine IT, HR, accounting, and administrative support that is not part of the core business and involves no unique intangibles — a cost plus 5% mark-up may be applied without a comparables study. But watch the boundary: the OECD expressly excludes financial transactions and treasury functions from this simplified approach, so a treasury charge needs its own arm’s length analysis rather than the 5% shortcut. Confirm a service genuinely qualifies before relying on it — misclassifying a core or valuable service as low value-adding creates audit exposure.
Connected persons and KMP remuneration
For director and key-management remuneration, first establish whether Article 36 applies to the individual and business, including its exceptions. Where applicable, deductibility depends on market value and the business-purpose requirement. Compare the full package with genuinely comparable responsibilities, not a generic salary figure. Disclosure thresholds are separate from deductibility.
Read alongside the Article 36 assessment: FTA clarification CTP010: director and officer
Five benchmarking mistakes to avoid
These practical checks make the analysis easier to understand and review:
- Testing the wrong activity. Explain the transaction being tested and the financial segmentation used. If transactions are combined, document why analysing them together is appropriate.
- Choosing a PLI by habit. Explain why sales, costs or assets provide a meaningful denominator for this transaction, and reconcile the calculation to the accounts.
- Using an unexplained comparable set. Record the geographical search sequence and why the selected businesses are economically comparable.
- Changing the cost base without explanation. Document allocation keys, segmentation and exclusions so a reviewer can reproduce the result.
- Treating the study as one-and-done. Revisit the assumptions and financial evidence each year. A periodic search refresh does not replace checking whether the business or transaction has changed.
A worked example: reading the range
Illustrative example only—not a published market benchmark: assume a UAE routine distributor’s study produces an interquartile operating-margin range of 1.8%–4.5%, with a median of 3.1%. These invented figures explain the calculation; they should not be used to price another company’s transactions.
- If the distributor’s operating margin is 3.0%, it falls within this illustrative range. That supports the conclusion only if the method, comparable set and financial calculations are reliable.
- If it is 0.9%, it falls below the range. The FTA can adjust taxable income upward, and the adjustment should be made to the point that best reflects the facts and circumstances; it is not automatically the median or the nearest quartile.
This is why the choice of tested party, PLI, and comparable set is not a formality: a small change in any of them moves the range and, with it, your tax exposure.
Intercompany loan benchmarking: a different question
Illustrative scenario: a parent lends to its Dubai subsidiary. The working paper should let a reviewer understand the agreement, currency, term, repayment profile, security and borrower’s position. A distributor’s profit-margin range cannot answer whether that loan’s interest rate is appropriate. Present the financing evidence and pricing conclusion separately.
Director remuneration benchmarking: compare the role
Illustrative scenario: an owner also works as managing director. Prepare a role description, responsibilities, time commitment and breakdown of salary, bonus and benefits. Explain why the comparison roles fit this business. An ownership return and payment for actual executive work should not be described as though they were the same thing.
Management fees: evidence beyond the percentage
Illustrative scenario: a group company charges for shared accounting support. Assemble the service agreement, records of work delivered, cost schedule and allocation calculation. A reader should be able to trace what the UAE company received and how the charge was calculated; a mark-up percentage alone does not explain that story.
What a benchmarking report should contain
A useful report gives the finance team and reviewer a clear audit trail. Depending on the method, include:
- A description of the tested transaction and the group structure;
- The functional analysis (functions, assets, risks) and the choice of tested party;
- The selected method and, where applicable, profit level indicator, with reasons;
- The evidence sources, search dates and search strategy, including any reliable internal comparables;
- The quantitative and qualitative screening steps, with the accept/reject rationale for each comparable;
- The final comparable evidence and range, with the calculations and any adjustments explained;
- The conclusion — whether the tested result is within the arm’s length range;
- Supporting appendices (comparable financials and intercompany agreements).
This report supports both your Local File and the transfer pricing disclosure in your corporate tax return, and should be retained for at least seven years.
How SAIF Chartered Accountants can help
As an FTA-registered Tax Agent (TAN 30004113) established in the UAE in 1994, we prepare documented benchmarking studies that integrate directly with your transfer pricing documentation and your UAE corporate tax return. Our transfer pricing benchmarking study service covers functional analysis, comparable searches, PLI selection, the interquartile range, and the full benchmarking report — plus intercompany loan, royalty, and connected-persons benchmarking.
Need a benchmarking study for your UAE corporate tax filing?
Discuss your transactions, available records and the appropriate scope of a benchmarking study with our team.
Authority and verification
Official sources
- UAE Federal Tax AuthorityTransfer Pricing Guide CTGTP1: comparables, ranges, documentation and specific transactionsChecked 16 September 2026
- UAE Ministry of FinanceMinisterial Decision No. 97 of 2023: documentation thresholds and Local File scopeChecked 16 September 2026
- UAE Federal Tax AuthorityTax Returns Guide CTGTXR1, sections 9.3 and 16: disclosure schedulesChecked 16 September 2026
- UAE Federal Tax AuthorityCTP010: meaning of director and officer for connected-person paymentsChecked 16 September 2026
- OECDTransfer Pricing Guidelines 2022: method selection and comparabilityChecked 16 September 2026
Clear answers
Frequently asked questions
What is a transfer pricing benchmarking study in the UAE?
It is an analysis of whether related-party prices, rates or margins reflect arm’s-length conditions. The evidence and method depend on the transaction; not every exercise requires an external database, a profit level indicator or an interquartile range.
When is a benchmarking study required for UAE corporate tax?
Distinguish the Local File and Master File thresholds from the evidence needed for a particular transaction. Relevant thresholds include AED 200 million or more of Taxable Person revenue, or membership of an MNE group meeting the AED 3.15 billion threshold, subject to applicable scope rules and exceptions. A database report is not automatically required for every transaction.
Which databases are used for UAE transfer pricing benchmarking?
Benchmarking is typically performed using Bureau van Dijk Orbis and Amadeus, TP Catalyst by Moody’s, and specialised sources for loans and royalties. The database, search date, screening criteria, and accept/reject rationale for every comparable are documented so the study is transparent and reproducible for FTA review.
What is the interquartile range in transfer pricing?
The interquartile range covers the middle half of the selected comparable results. It can help assess a range, but does not fix unsuitable comparables. A result inside it is only useful evidence if the method and data are reliable; the median is not an automatic adjustment target.
What is the LVAIGS 5% rule?
For low value-adding intra-group services — routine IT, HR, accounting, and administrative support that is not core and involves no unique intangibles — the OECD simplified approach allows a cost plus 5% mark-up without a full benchmarking search. Financial transactions and treasury functions are excluded from this shortcut and require their own analysis.
How often must a benchmarking study be updated?
Review the study’s assumptions and financial evidence annually. A three-year comparable-search cycle may be appropriate where conditions remain unchanged, but is not a guarantee that an old study remains usable. Reassess earlier after material changes to functions, risks, transactions or markets.
What happens if my result falls outside the arm’s length range?
The FTA can adjust Taxable Income to the arm’s-length result that best reflects the facts and circumstances. The median is not automatic; the reliability of the range and the functional profile should support the selected point.
Is director salary benchmarking the same as company-profit benchmarking?
No. Remuneration analysis examines the services performed and comparable reward packages. Company-profit benchmarking examines an appropriate financial return for a business activity. The evidence should fit the question rather than reuse an unrelated margin study.
Can the same benchmark be used for an intercompany loan and management fees?
Do not assume that it can. A financing transaction and a support-service charge require different evidence. Identify the terms and activity first, then document the appropriate analysis for each.