Jump to a section
At a glance
Key takeaways
- UAE Corporate tax registration obligations and deadlines depend on the taxable person and applicable authority rules.
- Late or incorrect registration can create penalties and delay later return-filing work.
- Registration details should match the entity’s licence, legal records and Federal Tax Authority profile.
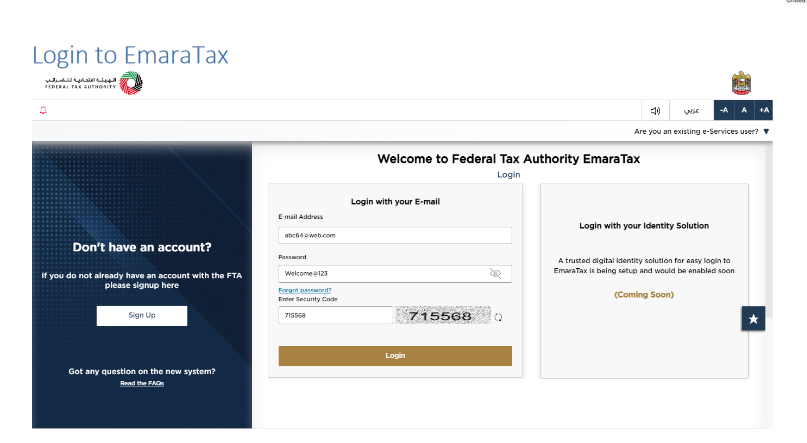
UAE Corporate tax registration is a separate obligation from filing and paying Corporate tax. The person must first determine whether it is required to register, identify the applicable deadline, and ensure that the EmaraTax profile matches its legal records.
Who must register?
Taxable juridical persons and other persons within the scope of the Corporate tax Law generally must register in accordance with the prescribed timelines. Free Zone Persons must register even where they expect to qualify for a 0% rate on Qualifying Income. A natural person is generally required to register when Turnover from UAE Business or Business Activities exceeds AED 1 million in a Gregorian calendar year; wages, personal investment income and real-estate investment income are excluded from that Turnover test.
Registration deadlines are not one universal number
The deadline depends on the person’s legal form, incorporation or recognition date, licence details and other rules in the current FTA registration-timeline decision. Do not apply a generic “90 days from incorporation” statement to every company. Check the current FTA service page and decision for the specific taxpayer.
Late registration penalty and waiver initiative
The FTA states that the administrative penalty for late Corporate tax registration is AED 10,000. Under the current waiver initiative, an eligible person can obtain relief when it completes registration and submits its first Corporate tax Return—or the applicable annual declaration for an Exempt Person—within seven months from the end of its first Tax Period or Financial Year. The waiver concerns the late-registration penalty; it does not replace the ordinary registration, return or payment obligations.
Information commonly needed for registration
- trade licence and constitutional or incorporation documents;
- registered address and contact details;
- owners, partners, directors and authorised-signatory information;
- financial year and first Tax Period details;
- branches, tax groups and Free Zone status where applicable; and
- supporting identification and authorisation documents.
After the Corporate tax Registration Number is issued
The taxpayer should verify the registration certificate, maintain accurate accounting records, identify its first Tax Period, establish the return and payment deadline, and keep its EmaraTax data current. Registration does not by itself determine the final tax rate, QFZP status, Small Business Relief eligibility or taxable income.
Common registration errors
- using an outdated deadline table or applying another entity’s deadline;
- entering a financial year that does not match the legal and accounting records;
- omitting branches, licences or ownership details;
- assuming a Free Zone company or a loss-making company does not need to register; and
- waiting for a penalty notice before checking the first return deadline.
How SAIF Chartered Accountants can help
Our tax team can assess registration status, confirm the applicable timeline, prepare the EmaraTax application, review the first Tax Period and coordinate the subsequent Corporate tax Return and accounting requirements.
Authority and verification
Official sources
- UAE Federal Tax AuthorityCorporate Tax Registration service and current FAQsChecked 21 August 2026
- UAE Federal Tax AuthorityWaiver of penalties for late Corporate Tax registrationChecked 21 August 2026
Clear answers
Frequently asked questions
Is UAE Corporate tax registration mandatory for Free Zone companies?
Free Zone Persons must register for Corporate tax even when they expect to qualify for a 0% rate on Qualifying Income.
What is the penalty for late Corporate tax registration?
The FTA states that the administrative penalty for late Corporate tax registration is AED 10,000.
How does the late-registration penalty waiver work?
An eligible person can obtain relief by completing registration and submitting its first Tax Return—or applicable annual declaration—within seven months from the end of its first Tax Period or Financial Year.
When must a natural person register for Corporate tax?
A natural person is generally required to register when Turnover from UAE Business or Business Activities exceeds AED 1 million in a Gregorian calendar year, subject to the statutory exclusions and current FTA deadline rules.
Does registration mean the business owes 9% Corporate tax?
No. Registration is an administrative obligation. The actual tax rate and liability depend on taxable income, exemptions, reliefs and any applicable Free Zone rules.